India's Supreme Court Lets Corruption Case Against Ex-NSE Chief Chitra Ramkrishna Proceed
Supreme Court refuses to quash Delhi HC order, allowing corruption charges against former NSE CEO Chitra Ramkrishna to go to trial.
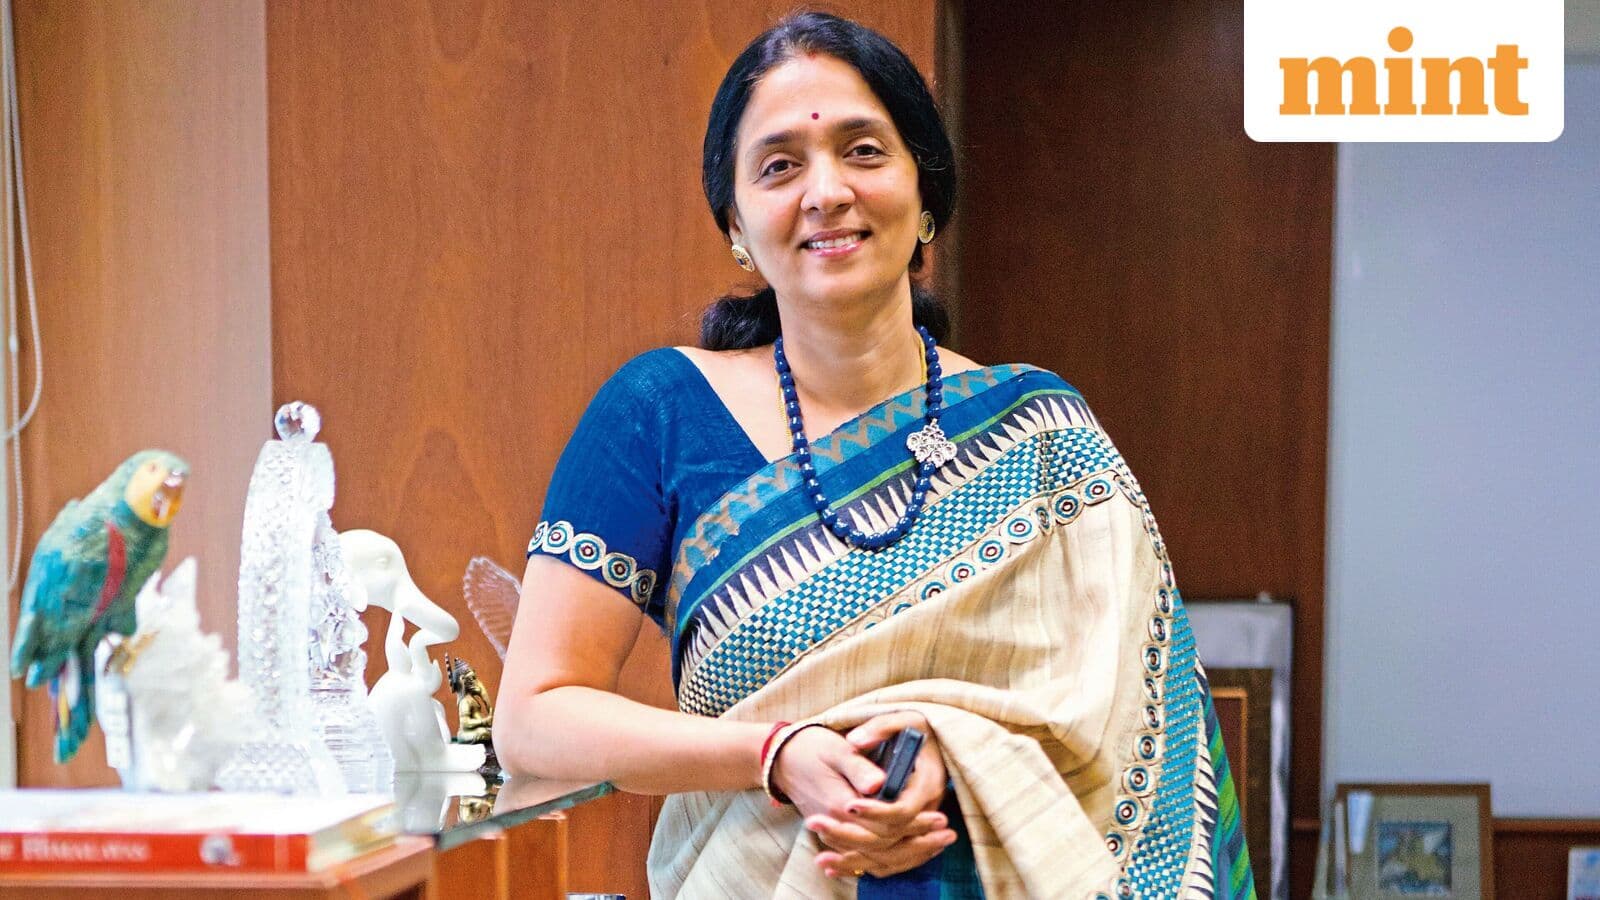
India's Supreme Court has handed the country's securities regulator a quiet but consequential victory, declining to interfere with a Delhi High Court ruling that allows corruption charges to proceed against Chitra Ramkrishna, the former managing director and chief executive of the National Stock Exchange. For anyone tracking how Asia's financial gatekeepers are policed, the signal is blunt: the men and women who run the region's most important market infrastructure can be treated as public servants when things go wrong, and the courtroom, not the boardroom, will decide the rest.
The case itself turns on a deceptively technical question. Ramkrishna had asked the Supreme Court to quash the High Court's rejection of her plea challenging her prosecution under the Prevention of Corruption Act. Her counsel, Senior Advocate Balbir Singh, argued that she did not hold office under a regulatory or governmental framework, and that the PC Act could not be invoked against her. A Bench of Justices JB Pardiwala and K Vinod Chandran was unmoved. The High Court had already held that the NSE discharges a public duty, and that Ramkrishna, as its MD and CEO, could not be wholly divorced from the exchange's functions, in which the public has an interest. The Supreme Court said no error could be said to have been committed, while leaving the public-servant question open for the trial court to decide on its own merits. It also observed that the special court would not lose jurisdiction merely if it ultimately held that she was not a public servant.
The underlying allegations are anything but technical. They stem from a February 11 order by the Securities and Exchange Board of India, which found Ramkrishna allegedly involved in financial misdeeds related to the fixation and frequent upward revisions of compensation for another former NSE executive, Anand Subramanian. She allegedly carried out these actions in collusion with an individual she claimed was a 'Siddha Purusha.' The Central Bureau of Investigation has alleged that Subramanian, while performing a public duty to safeguard the interests of common investors, entered into a criminal conspiracy with other co-accused to confer substantial advantages upon select trading members and brokers. Another central allegation is that Ramkrishna maintained frequent email contact with an unknown Himalayan Yogi, whom the CBI later alleged was Subramanian himself.
For outsiders, the NSE is not merely a stock exchange. It is the plumbing through which tens of millions of Indian households, pension funds and foreign institutions route their savings into the world's fifth-largest economy. Its credibility is a national asset. The idea that its former chief could be prosecuted under anti-corruption law, rather than only under the Indian Penal Code, matters because it widens the aperture of accountability. The High Court's reading of the PC Act's definitions, that 'public duty' covers any duty in which the State, the public or the community at large has an interest, and that a 'public servant' includes anyone authorised or required to perform such a duty, effectively pulls private or quasi-private market institutions into the same ethical orbit as government bodies.
The Supreme Court's refusal to quash the High Court order does not convict Ramkrishna. It does not even finally decide whether she was a public servant. What it does is allow the prosecution to proceed, and it sends a message that India's courts are willing to let trial judges wrestle with the boundary between private management and public trust. The Court's remark that Ramkrishna 'should not have invited a High Court order' suggests a certain impatience with attempts to short-circuit the process. For a region where family conglomerates and state-linked exchanges often blur the line between private and public interest, this is a case worth watching closely. The next chapter will be written in the trial court, and its outcome could shape how Asia's market overseers are held to account for years to come.