Kelvin Obasuyi: Nigeria's Payment Delays Are Quietly Raising the Cost of Trade
Fintech founder Kelvin Obasuyi argues that slow cross-border settlement, not just scarce credit, is inflating working-capital needs for Nigerian traders.
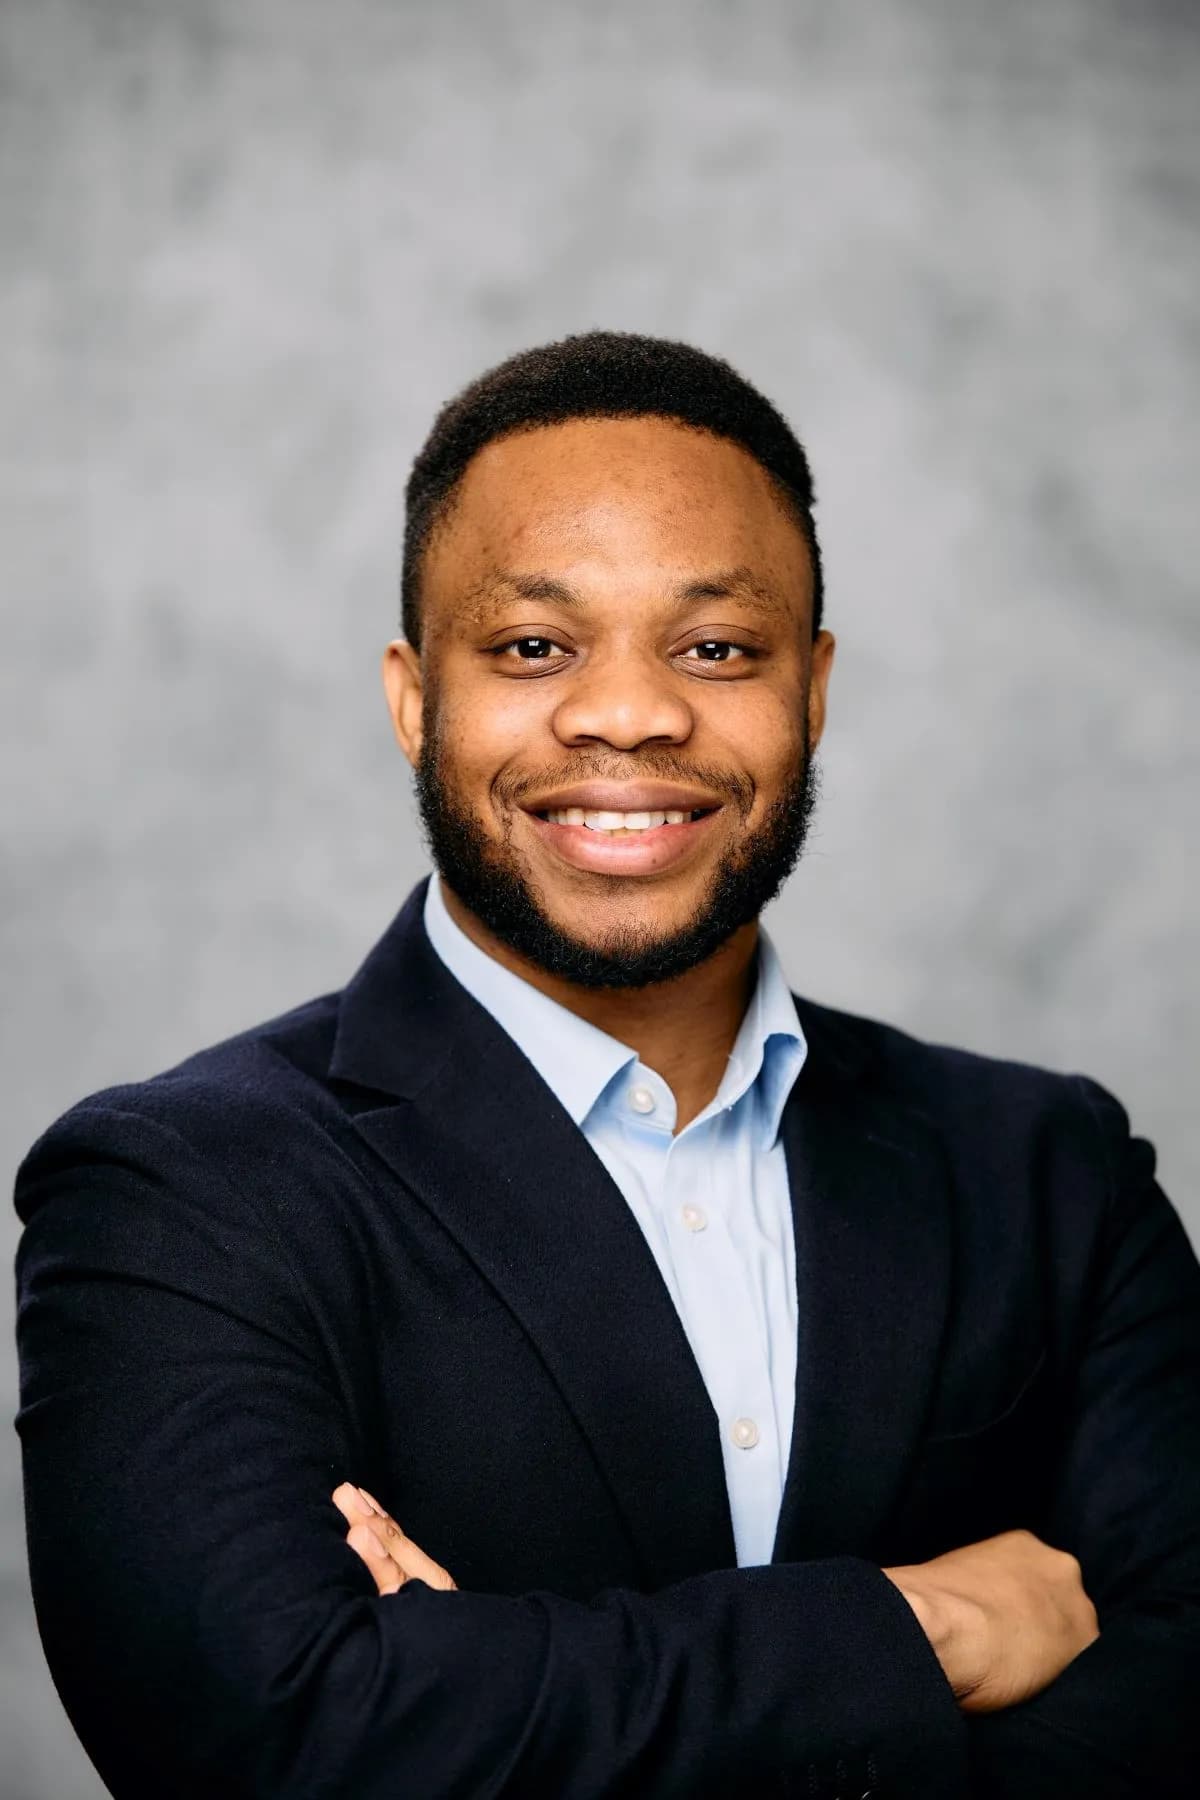
For every Nigerian importer who has wired funds and then waited, goods stuck behind a supplier's compliance desk, Kelvin Efosa Obasuyi has a diagnosis that rarely makes the loan-application spreadsheet: the money was there, it simply could not be deployed when it was needed. That distinction, he argues, sits at the heart of why trade keeps getting more expensive for African businesses than the headline transfer fee suggests.
Obasuyi is the founder and chief executive of Vector Innovation, a cross-border payments and treasury infrastructure firm, and a co-founder of 56 Capital, a business-financing company. His argument, made in comments reported by Nairametrics, is that payment infrastructure deserves a seat in the SME financing conversation that it has so far been denied. A company can hold enough capital to complete a transaction and still fail to deploy it at the moment the supplier demands cleared funds, the exporter awaits proceeds for the next production run, or an obligation falls due in a currency the business does not hold in the right account.
The mechanics matter because they compound. An importer who has paid for inventory but cannot confirm the supplier has received cleared funds may need to borrow again to keep operations moving. An exporter that has shipped but cannot touch the proceeds may delay the next order, or decline it outright. For firms with thin reserves, the response is usually more debt, postponed purchases or a lost contract. Obasuyi's view draws on three vantage points: assessing borrowers at 56 Capital, building fintech products at Duplo, and constructing cross-border payment rails at Vector. Each role approached the same problem from a different side, how businesses raise capital, read their own financial position and move money to keep commerce alive.
The local context is a Nigerian SME sector that already borrows at some of the continent's steepest rates, where access to credit dominates policy debate. What Obasuyi adds is a working-capital lens: a financing facility may buy the stock, but the gap between payment, delivery, sale and collection determines how long that facility stays outstanding. Stretch the cycle through settlement delays and the financing requirement grows even when the underlying order remains profitable. The true cost is not the transfer fee or the exchange-rate quote, but the time capital stays locked, the reserves held against uncertainty and the opportunities forgone while waiting.
That has implications on both sides of a trading relationship. A British supplier selling to a Nigerian distributor needs a dependable basis for deciding when to release inventory or extend terms; the Nigerian buyer needs clarity on funding, conversion and settlement timing before committing to its own customers. Where timing is uncertain, suppliers demand funds earlier and buyers hold larger buffers, arrangements that protect each counterparty while tying up more capital across the relationship. Obasuyi's early experience at Vector sharpened this: he expected price and geographic coverage to drive customer choice, but conversations kept returning to dependable settlement, transparency and responsiveness. Behind an urgent transfer is usually a supplier waiting to release goods, a finance team queuing another authorisation, or a contract deadline closing in.
For a continent whose trade is increasingly cross-border and currency-fragmented, that is a wealth story as much as a payments one. Capital that cannot move on time is capital that costs more to hold, and African businesses pay for that friction in reserves and forgone growth. Obasuyi's prescription is modest but pointed: payment providers should understand the commercial purpose behind a transaction and give customers the information to plan around it. If that sounds like infrastructure rather than fintech hype, it is. The next wave of African trade competitiveness may be decided not by who can borrow cheapest, but by who can move money with certainty.