Ziina's CEO Makes the Case for Open Finance as MENA's Next Wealth Infrastructure
Ziina co-founder Faisal Toukan argues Open Finance can close MENA's SME financing gap by connecting fragmented financial data across institutions.
Faisal Toukan wants the Middle East's financial system to stop treating fragmentation as a feature. The co-founder and CEO of Ziina, a UAE-based payments company, has published an argument that lands squarely in the middle of the region's most consequential financial debate: who gets to see the full picture of a business's money, and what that visibility is worth.
The pitch is straightforward. Digital banks, payment platforms, accounting software and investing apps have each solved a discrete problem over the past two decades. What none of them solved is the connective tissue between them. A business can collect payments in one system, hold cash in another, invoice somewhere else and keep its books on a fourth platform. The owner becomes the integration layer. Toukan calls this the gap between what the industry sells as separate products and what the customer experiences as one financial life. The cost is not just administrative annoyance. It is productivity, and ultimately capital allocation. The International Finance Corporation, using 2019 data, estimated the financing gap for micro, small and medium-sized enterprises across emerging and developing economies at $5.7 trillion. In MENA, those gaps ranked among the largest relative to GDP, averaging close to 30%.
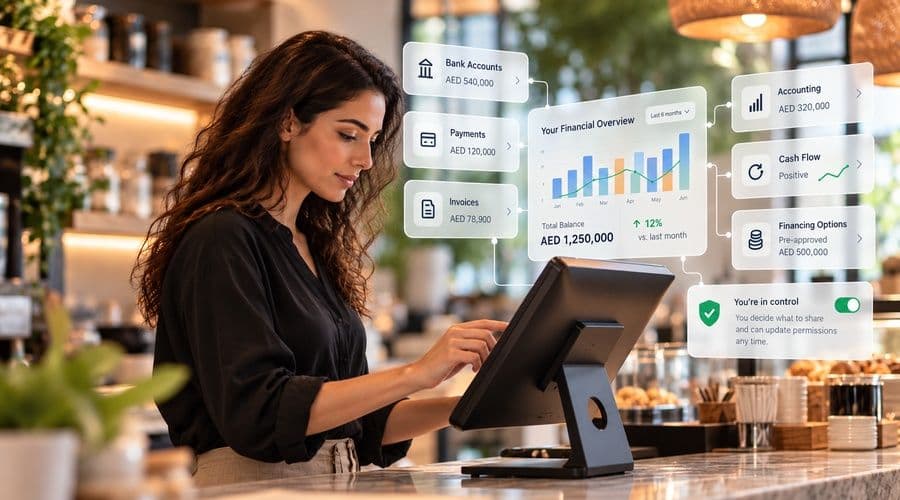
Ziina is not a household name outside the Gulf, but it sits in a crowded and well-funded corner of the UAE's fintech scene: consumer and merchant payments aimed at younger users and small businesses. Toukan's argument is notable because it comes from an operator, not a regulator or a consultant. He describes a scenario in which a customer payment triggers a chain reaction — the bank account updates, the accounting platform syncs, cash-flow projections refresh, working capital recalculates, financing options adjust. The payment is the starting point, not the end. For consumers, the same logic applies: income, savings, investments and recurring commitments combine into something more useful than isolated snapshots. Artificial intelligence makes the interaction conversational, but connected systems give it context.
The mechanism he points to is Open Finance, which extends the concept of Open Banking beyond bank account data to a broader range of financial products and services. The UAE's Central Bank has been building this at the ecosystem level, introducing a common infrastructure framework. That regulatory groundwork matters for a region where capital often moves across borders faster than data does. For wealth managers, family offices and lenders operating across the Gulf, the promise is a more complete view of a borrower or client without the usual manual reconciliation. The risk, as always, is consent and execution. Toukan notes that data sharing must be subject to customer permission and limited to the services connected to the system.
What makes this more than a fintech talking point is the wider economic backdrop. MENA's small and medium-sized enterprises are the backbone of employment in markets from Egypt to Jordan to the UAE, yet they remain chronically underbanked relative to their revenue and cash flow. A business with healthy customers and predictable income can still fail to secure working capital because the signals that prove its health are scattered across incompatible systems. The institution making the lending decision sees only its own slice. The business lives the whole picture. Closing that information gap is not a technology problem anymore. It is an infrastructure problem, and infrastructure is exactly what the UAE has been trying to build.
The next phase will test whether Open Finance becomes a genuine layer of the region's financial architecture or remains a regulatory aspiration. Banks, payment providers, lenders and accounting platforms all have incentives to participate, but also to protect their customer relationships. Toukan's bet is that the operators who connect the dots will capture more value than those who guard their silos. For a region pouring capital into digital transformation, that is the question worth watching.