Tabby's $6.5B round turns Saudi fintech into a sovereign-scale story
Tabby raised $233M at a $6.5B valuation, led by Blue Pool Capital, as the Saudi fintech expands from BNPL into broader finance.
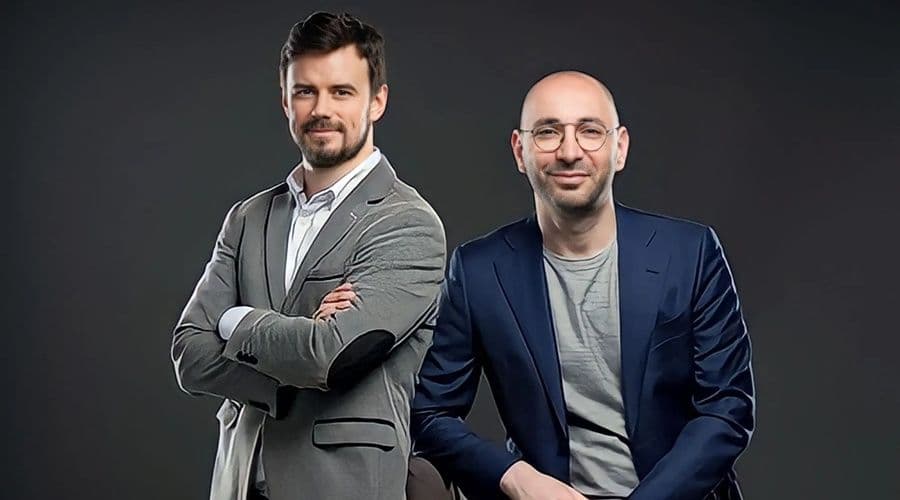
In Riyadh and Dubai, the phrase "fintech exit" usually trails a foreign acquirer. Not this time. Tabby, the Saudi-headquartered payments and credit platform, has closed a $233 million equity round at a $6.5 billion valuation — a number that would have looked absurd for a Gulf consumer finance app five years ago, and now reads as the region's answer to a neobank. For anyone tracking where Middle East capital is going, this is the signal: the kingdom's consumer credit story is no longer a sideshow to oil.
The round was led by Blue Pool Capital, an existing investor, with HSG, Wellington Management and Arbor Ventures also returning. Those are not typical Gulf venture names; they are institutional pools that treat the region as an allocation, not a novelty. Tabby says it has been profitable since 2023 and processes more than $18 billion in annualised transaction volume across 25 million registered users and 70,000 business partners. The new valuation is roughly 44% above the $4.5 billion mark from a secondary sale in October 2025, and nearly double the $3.3 billion attached to its $160 million Series E in February 2025. No revenue figures were disclosed, and the company did not publish a net income number — a reminder that "profitable" in a press release is not the same as audited profit.
To understand why this matters outside the Gulf, you need the local context. Tabby was founded in 2019 by Hosam Arab and Daniil Barkalov, starting as a buy now, pay later button at online checkouts — the kind of product that lets a Saudi shopper split the cost of a phone or a flight without a credit card. That market was historically underserved: until recently, many Gulf consumers relied on cash, debit or family lending, and formal credit was often reserved for salaried employees with long banking relationships. Tabby's early edge was speed and a checkout integration, not a banking licence. What has changed is that it now holds one. In Saudi Arabia, the Saudi Central Bank has granted Tabby consumer and SME finance licences, letting it offer larger and longer-term financing to individuals and working capital to businesses. It also acquired Tweeq, a SAMA-licensed digital wallet, pushing it into accounts, cards and transfers. In the UAE, it secured a Stored Value Facilities licence to launch Tabby Cash, a no-fee alternative to a debit account with cashback and local and international transfers.
That regulatory shift is the real story. BNPL is a thin-margin, high-churn business; licensed lending and deposits are not. By stacking a wallet, cards, transfers and SME credit on top of its checkout base, Tabby is trying to become the primary financial relationship for a young, mobile-first population that Gulf banks have long treated as too small to serve profitably. The employee liquidity option in the round — Tabby has run share tenders since 2023 and facilitated more than $100 million in share sales — is also a quiet milestone. In a region where startup wealth has often been paper wealth, letting current and former staff cash out before an IPO is how you build a repeat-founder culture.
The wider signal for Middle East wealth is about where the smart money is rotating. For a decade, Gulf capital chased real estate, ports, telecoms and, more recently, AI data centres. Consumer fintech was seen as a venture bet, not a sovereign priority. Tabby's valuation trajectory — from $3.3 billion to $4.5 billion to $6.5 billion in under a year — suggests that the region's digital consumer economy can now support institutional-scale outcomes without a foreign buyer. It also puts pressure on the region's banks, which have watched fintechs nibble at payments and now face a licensed lender with 25 million users and a wallet of its own.
The deal is not closed. Tabby notes the transaction remains subject to applicable regulatory approvals, including from SAMA. That caveat matters: Saudi regulators have been supportive of fintech but deliberate, and a $6.5 billion valuation on a company that still does not disclose revenue will invite scrutiny. The next test is not another round. It is whether Tabby can convert licences into deposits, deposits into lending, and lending into the kind of durable earnings that justify a valuation that now dwarfs many listed Gulf financial firms. If it can, the kingdom will have produced its first true consumer finance champion. If it cannot, the round will be remembered as the moment Gulf fintech learned to price ambition — and to live with it.


