erad's $22 Million Series A Bets Shariah-Compliant Fintech Can Close the Gulf's SME Credit Gap
Saudi fintech erad raises $22M Series A led by MEVP to scale Shariah-compliant SME financing across the GCC, targeting a $250B regional credit gap.
Saudi Arabia's small and medium businesses have a habit of growing faster than the banks can keep up with. erad, a Riyadh-based fintech founded in 2022, is betting that speed, data and Shariah compliance can turn that mismatch into one of the Gulf's more consequential lending businesses. On the back of 8x year-over-year growth in the Kingdom, the company has closed a $22 million Series A (SAR 78.75 million) led by MEVP, with new money from 500 Global, Saudi Venture Capital, S60 Ventures, ANB Capital, Conjunction Capital and Araya Ventures, and continued backing from Khwarizmi Ventures, Nuwa Capital, Aljazira Capital, Oraseya Capital and Joa Capital.
The numbers behind the raise explain the investor appetite. erad has deployed more than SAR 500 million ($133 million) in cumulative financing to SMEs and says it has fielded over SAR 4 billion ($1 billion) in financing requests to date — a ratio that speaks less to erad's marketing than to how starved Gulf small businesses are for working capital. Its pitch is straightforward: financing of up to SAR 10 million, fully Shariah-compliant, with approvals averaging 48 hours, powered by proprietary AI models that track client cash flows and underwrite risk in near-real time. Roughly 85% of clients expand their financing within the first year, according to the company. The November 2025 announcement of a $125 million scalable facility led by Jefferies gave erad a balance-sheet backbone to match its software ambitions.
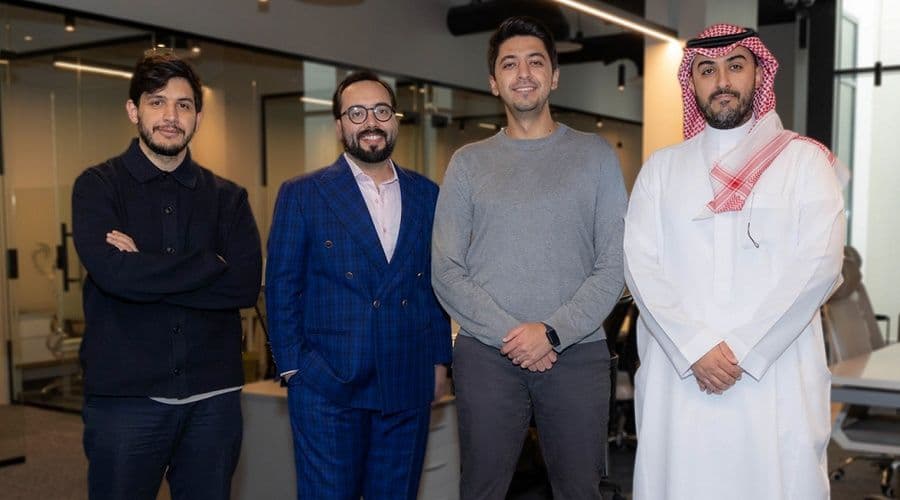
For readers outside the region, the Shariah-compliant label is not a niche detail. It is the price of admission. Interest-bearing lending is off the table for a large share of Gulf businesses, and Islamic finance structures — profit-sharing, cost-plus sales, leasing — are the default vocabulary of corporate credit from Riyadh to Dubai. A fintech that can underwrite at speed while staying inside those rules addresses a segment that conventional banks have long served slowly, if at all. erad's founding team — Salem Abu-Hammour, Faris Yaghmour, Abdulmalik Almeheini and Youssef Said — is selling into a market where the regulatory tailwind is real: Saudi Vision 2030 has made SME lending a national priority, and the Saudi Venture Capital Company's participation in this round is a signal that Riyadh sees private credit as infrastructure, not speculation.
MEVP's Jad El Boustani framed the opportunity in numbers that should interest anyone tracking Gulf capital: a $250 billion SME financing gap across the GCC. That gap is the region's quiet structural problem. SMEs account for roughly half of regional GDP and two-thirds of employment, yet they remain underbanked relative to their contribution. erad's expansion beyond its original target sectors into logistics, medical equipment and wholesale distribution — and its stated focus on capital-intensive industries like industrial and manufacturing — suggests the company is moving up the risk curve deliberately, using data rather than collateral as its primary underwriting tool.
The Gulf's venture market has matured enough that a Series A of this size is no longer remarkable on its own. What is notable is the composition of the cap table: a Lebanese-founded regional fund in MEVP, a Saudi state-backed investor in SVC, global names like 500 Global, and a cluster of Gulf family-office and bank-linked vehicles. That mix — sovereign, institutional and private Gulf capital sharing a register — is increasingly the template for how scale-up fintechs get funded in the region. It also reflects a broader shift: Gulf wealth is rotating from real estate and passive holdings toward operating businesses in sectors governments have designated as strategic.
erad's next chapter will test whether its model travels. The company plans to deepen its presence across the GCC, build new products for industrial, logistics and manufacturing clients, and grow its technology and commercial teams. The harder question is whether a 48-hour approval engine can maintain its risk discipline as ticket sizes rise and the borrower base diversifies beyond the trading businesses that first embraced it. For now, the money is in place, the demand is documented, and the region's SME credit gap remains wide enough to absorb far more capital than erad has raised. The interesting part starts when the easy growth is behind it.